Compound Research
Which UK professions sit inside the tax traps?
Most coverage of the 60% tax trap talks about abstract salary bands. We did something different: we took published national pay scales and mapped the actual pay points onto the 2026/27 tax bands. The result is that some entire career structures are built through the worst rates in the system.
Published 25 July 2026 · Modelled by Compound Money for the 2026/27 tax year · Free to reproduce with attribution and a link
The headline: an NHS consultant's first eight years
The consultant contract in England has five pay thresholds. Three of them sit inside the £100,000 to £125,140 band where the personal allowance is withdrawn:
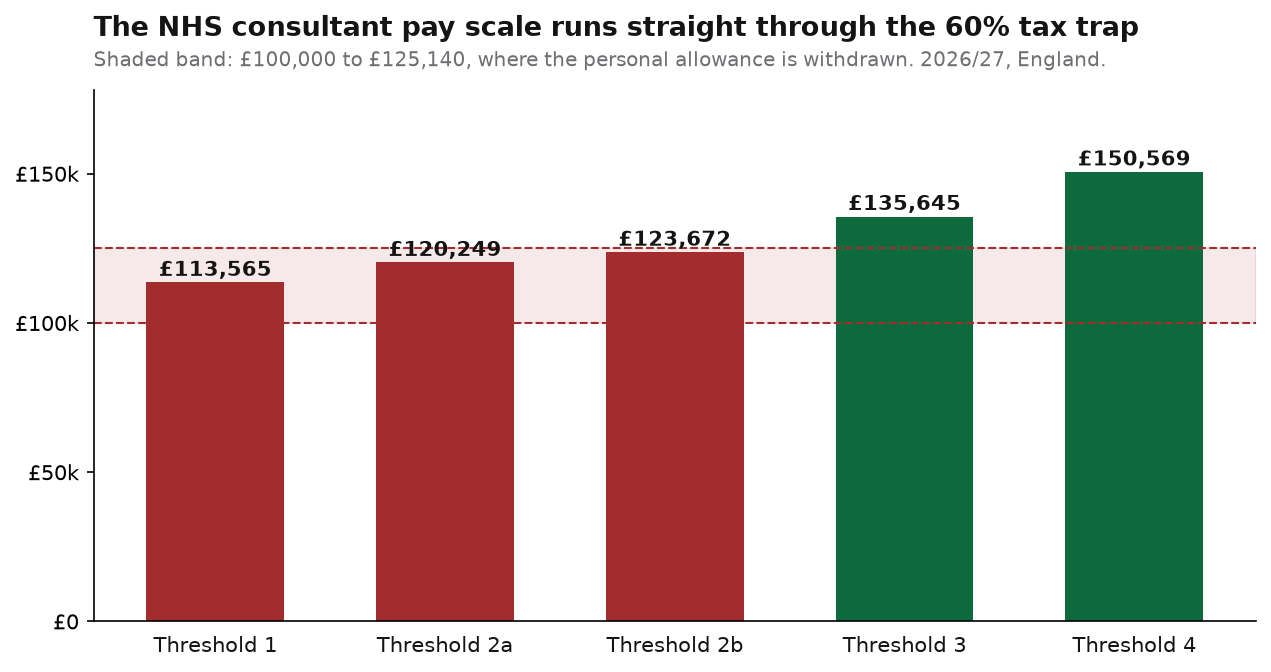
Threshold 1 (entry, £113,565), Threshold 2a (after 3 years, £120,249) and Threshold 2b (after 4 years, £123,672) all fall inside the band. A consultant only climbs clear of it at Threshold 3, which takes eight years of service. On gross pay alone, a newly appointed consultant faces a 62% effective marginal rate, rising to 71% with two children and a Plan 2 student loan.
Free Guide
Get the Compound Playbook
Every core move for building wealth in the UK, in one free PDF. Charts, worked examples and a cheat sheet.
Free PDF plus occasional tips and offers. Unsubscribe anytime. Privacy.The league table
Effective marginal rate on the next £1 of gross salary, 2026/27, England and Wales. "With children" assumes two children and Child Benefit in payment; the loan column adds a Plan 2 student loan.
| Pay point | Salary | Single | 2 children | 2 children + loan |
| NHS consultant, entry (Threshold 1) | £113,565 | 62.0% | 62.0% | 71.0% |
| NHS consultant, 3 years (2a) | £120,249 | 62.0% | 62.0% | 71.0% |
| NHS consultant, 4 years (2b) | £123,672 | 62.0% | 62.0% | 71.0% |
| NHS consultant, 8 years (3) | £135,645 | 47.0% | 47.0% | 56.0% |
| NHS consultant, 14 years (4) | £150,569 | 47.0% | 47.0% | 56.0% |
| Headteacher, bottom of London fringe range | £62,101 | 42.0% | 53.3% | 62.3% |
| Headteacher, top of London fringe range | £150,301 | 47.0% | 47.0% | 56.0% |
| UK median full-time employee | £39,039 | 28.0% | 28.0% | 37.0% |
Two findings worth pulling out
- Career structures, not just salaries, run through the traps. The consultant scale is not an accident of one person's pay: it is a national contract whose first three thresholds all sit in the 60% band. Every consultant in England passes through it.
- A headteacher at the bottom of the London fringe range faces a higher marginal rate than one at the top. At £62,101 with two children and a student loan the rate is 62.3%; at £150,301 it is 56%. The tax system is not monotonic, and the Child Benefit charge is why.
The important caveat: pensions change this
These figures use gross salary. Both professions have significant occupational pension schemes, and employee contributions reduce the adjusted net income the tax traps are measured against. A consultant contributing to the NHS pension scheme, or a teacher to the Teachers' Pension Scheme, will have a lower adjusted net income than their headline pay point, which can move them down a band or out of a trap entirely.
That is not a footnote, it is arguably the most useful thing here: pension contributions are the main lever these professions have, and their effect is largest precisely in the bands where the marginal rate is worst. Model your own position with the High-Earner Tax Optimiser, which handles the taper, the Child Benefit charge and student loans together.
Method and sources
- Pay points: published national pay scales, not estimates. NHS consultant thresholds are the England 2026/27 scale following the 3.5% DDRB award (BMA). Headteacher figures are the London fringe leadership pay range under the School Teachers' Pay and Conditions Document. The median is ONS ASHE 2025 (£39,039, provisional).
- Tax: 2026/27 England and Wales. Personal allowance £12,570, tapered by £1 per £2 above £100,000; higher rate from £50,270; additional rate from £125,140. Employee National Insurance 8% and 2%. High Income Child Benefit Charge tapering between £60,000 and £80,000. Plan 2 student loan at 9% above £29,385.
- Marginal rate is the proportion of the next £100 of gross salary lost to tax, National Insurance, Child Benefit withdrawal and student loan repayment.
- Excluded: occupational pension contributions (see caveat above), Scotland's separate income tax bands, and any local or regional supplements such as London weighting on the consultant contract.
For journalists
These figures are free to reproduce with attribution to Compound Money and a link to this page, and the chart may be republished. We can run the same mapping for any other published pay scale (police, civil service grades, academia, armed forces) on request: hello@compoundmoney.co.uk.
General information, not financial or tax advice. Figures are modelled from published pay scales and 2026/27 tax rules and will differ from any individual's position, particularly where pension contributions, supplements or Scottish rates apply.